Operating a warehouse means balancing speed, safety and accuracy. When stock differences keep returning, dispatches fall behind or a customer asks for evidence, a warehouse audit helps you examine what is happening and decide what needs to change.
Download an editable Excel workbook, printable PDF floor sheets and completed examples for your team.
Excel and PDF audit packPreview pack contents and download
Bring these 28 checks into an editable working record and printable floor sheets, with examples to help you record findings and assign follow-up.
- Editable Excel workbook: plan the review, record evidence and track findings, action owners and verification.
- Printable PDF sheets: take the checklist onto the warehouse floor and make notes as you review.
- Completed examples and a management review template: see how a stock investigation and provider review become findings, assigned work and decisions to follow up.
Your audit pack is ready
What is a warehouse audit?
A warehouse audit is a planned review of how a warehouse operates against the requirements it needs to meet. It compares procedures and records with what happens on the floor, then records the findings and the work needed to address them.
The reason for the review determines its scope. An inventory lead investigating repeated stock differences needs different evidence from a director reviewing a warehouse provider before renewal. Start with the question you need answered, then choose the relevant areas below.
This checklist reviews an existing physical warehouse. Daily task lists and pre-use inspections help people carry out particular work; a wider audit examines whether the processes and controls work as intended. Opening a new warehouse calls for a setup and launch plan. For analytical databases or mortgage lending, the relevant subjects are data-warehouse auditing and mortgage warehouse lending.
The Practical Warehouse Audit Checklist
Work through the areas relevant to your warehouse. Add the customer, product or legal requirements that each check needs to cover.
Open a question for inspection prompts and follow-up guidance. For equipment checks, training and emergency preparation, see our warehouse safety checklist.
Inventory accuracy and storage
-
Count versus recordDo the quantities in selected locations agree with the inventory records for the same point in time?
Check against Establish the item, unit, location, count boundary and comparison time before interpreting a difference.
Look for Compare count notes with stock records and movements around the count; retain the sample, timing and any recount.
Follow up Resolve timing or unit uncertainty, record the unexplained variance and assign investigation before treating an adjustment as closure.
-
Item, location and unit identityCan the team distinguish the item, storage location and handling unit without having to guess?
Check against Check against the operation's agreed item, location and unit definitions, including relevant pack-size changes.
Look for Trace selected labels, item records, locations and transaction entries; ask workers how similar-looking products or changed packs are distinguished.
Follow up Record the specific ambiguity and affected transactions, then identify who can correct the definition and check the resulting records.
-
Discrepancies and recurrenceWhen stock discrepancies return, does the team investigate what happens between counts?
Check against Establish how discrepancies should be reported, investigated and closed, separately from correcting the balance.
Look for Follow selected recurring differences through adjustments, movement records, worker accounts and earlier actions; retain competing explanations and gaps.
Follow up Assign the next evidence request and an investigation owner. Identify what a later check would need to show before calling the problem resolved.
Receiving through dispatch
-
Receipt identification and exceptionsCan you trace what arrived, what was accepted and what happened to any discrepancy?
Check against Identify the receipt, acceptance and exception requirements for the goods and transaction being reviewed.
Look for Compare expected shipment details, receipt records and recorded damage or shortages; ask who decided the disposition and informed the next team.
Follow up Record any missing decision or broken record link, and assign the person responsible for resolving that receipt exception.
-
Putaway and staging handoffsDo accepted goods reach the intended storage location with their status and records still clear?
Check against Confirm the site's putaway, staging and exception arrangements for the goods, including who owns each handoff.
Look for Trace selected receipts from staging to storage and record updates; observe delays, unclear ownership or goods awaiting a decision.
Follow up Separate an unrecorded movement from a physical delay, establish the dependency and assign the next responsible action.
-
Picking and dispatch verificationCan the team connect the authorised order, prepared goods and recorded release to the same shipment?
Check against Establish the operation's order, verification and release requirements, including authority to resolve a mismatch.
Look for Compare selected pick or release instructions, item quantities, shipment records and handover details; examine how changes or shortages were communicated.
Follow up Identify the failed or uncertain handoff and its owner. Keep checking this shipment distinct from reviewing recurring process failures.
-
Arrival timing and resource coordinationDoes the team have the information and resources needed for the arrivals and departures it must handle?
Check against Establish the relevant service commitments, operating constraints and responsibilities for communicating or changing the plan.
Look for Compare planned and actual timing with workload, staffing, available space and exception records across selected operating periods.
Follow up Investigate which constraint affected service before choosing an intervention; assign any unresolved coordination or resource decision to its owner.
Warehouse layout and flow
-
Usable space and congestionWhere does work queue or spill into space needed for another activity?
Check against Confirm the intended use and relevant constraints of each area for the operating conditions being examined.
Look for Observe selected busy and quieter periods; compare queues, space use, workload and available resources with the plan and worker explanations.
Follow up Distinguish a recurring constraint from an isolated event, and identify the evidence needed before changing capacity or layout.
-
Slotting, travel and replenishmentDoes the placement of stock support the picking, replenishment and handling work people actually perform?
Check against Establish the relevant product, handling, access and workload requirements rather than assuming one arrangement suits every item.
Look for Follow selected pick and replenishment paths; compare item activity, travel, repeated interruptions and worker accounts with the placement rationale.
Follow up Record the constraint and competing explanations, then identify who should assess a proposed change and its effects.
-
Housekeeping and recurring obstructionsWhen clutter or obstructions return, is there a clear owner and an explanation beyond clearing them again?
Check against Identify the site's relevant housekeeping, access and storage requirements and the responsibility for acting on exceptions.
Look for Compare current observations with earlier reports, assigned work and worker accounts of why material accumulates.
Follow up Follow the site's response arrangements for current concerns, then assign investigation of recurring causes and a check that the action worked.
Equipment and machinery
-
Inspection and maintenance coverageAre the equipment inspections and maintenance required for this operation identifiable, assigned and supported by records?
Check against Confirm the applicable equipment instructions, inspection requirements and competence needed with the responsible equipment owner.
Look for Match selected equipment to its identity, inspection and maintenance records, due work and the people responsible.
Follow up Refer missing coverage or uncertain criteria to the appropriate owner or competent reviewer; do not fill the gap with a generic checklist.
-
Defect reports and operating restrictionsCan people report an equipment defect and find out what restrictions or action apply?
Check against Establish the defect-reporting and response arrangements, including who is authorised to assess the equipment.
Look for Trace selected defect reports to decisions, communications and current operating status; ask affected workers what they were told.
Follow up Escalate missing or conflicting status information through the site's responsible owner. Keep any technical assessment with a person competent for that equipment.
-
Repair and return to useWhat evidence supports returning equipment to use after a reported defect or repair?
Check against Confirm the applicable acceptance requirements and who can authorise the change in operating status.
Look for Follow selected defects through repair records, assessment or checks required for acceptance, remaining restrictions and communication to users.
Follow up Keep missing acceptance evidence visible and refer the decision to the authorised owner; a completed work order alone may not answer the readiness question.
People and workplace safety
-
Site hazards and controlsDo the controls for identified site hazards match the work being performed?
Check against Establish the applicable hazard assessments, requirements and control arrangements with the responsible safety and operating owners.
Look for Compare recorded controls with observations, worker accounts, reported concerns and changes in goods, equipment or activity.
Follow up Route an immediate concern through the site's response process. Assign unresolved control questions to the competent owner and record the evidence still needed.
-
Competence and handoverDo people know how to perform their assigned work and pass unresolved issues to the next responsible person?
Check against Confirm the task's competence requirements and the site's arrangements for handover, exceptions and escalation.
Look for Compare preparation records with explanations and observed work; follow a selected unresolved issue across a shift or team boundary.
Follow up Identify whether the gap concerns preparation, instructions, authority or communication, then assign support and a suitable follow-up check.
-
Workload, worker accounts and practical constraintsWhat makes it difficult for people to follow the agreed process or report a problem?
Check against Establish the expected work, available resources and reporting responsibilities for the shifts and tasks reviewed.
Look for Combine worker accounts with workload, interruption and exception records; examine whether instructions or performance measures pull people in different directions.
Follow up Preserve differing accounts, test the explanation against records and observations, and escalate resource or authority constraints to the person who can change them.
Goods protection and specific requirements
-
Access, custody and loss controlsCan the operation account for who had custody of selected goods and how unexplained losses are handled?
Check against Identify the applicable custody, access and loss-reporting controls for the goods, ownership arrangement and review purpose.
Look for Trace selected goods through movement and handover records; compare any access records, loss reports and assigned investigations.
Follow up Separate a missing record from an established loss or wrongdoing, and assign unresolved custody or security questions to the appropriate owner.
-
Product condition and traceabilityCan the team establish the identity, recorded condition and relevant movement history of selected goods?
Check against Confirm the product, customer and applicable assurance requirements, including which identifiers and condition records matter.
Look for Trace selected goods through receipt, storage and release records, including condition exceptions, holds and disposition decisions where relevant.
Follow up Identify the break in the evidence chain and the responsible product or quality owner; preserve uncertainty about condition or acceptability until assessed.
-
Controlled goods and customs requirementsWhere controlled goods or customs arrangements apply, can the team identify the requirements and produce the relevant evidence?
Check against Name the actual goods, activities, jurisdiction and programme, then establish the applicable criteria with the responsible specialist.
Look for Compare selected movement, status and exception records with those criteria and any required permissions or declarations.
Follow up Record the precise unanswered requirement and assign its resolution to the appropriate compliance owner before drawing an assurance conclusion.
-
Storage conditions and environmental obligationsAre relevant storage conditions and environmental responsibilities defined, monitored and acted on when something goes wrong?
Check against Establish the goods, site and activity requirements and identify who determines acceptable conditions and responses.
Look for Review applicable monitoring records, exceptions, decisions and follow-up alongside observations of the relevant area or activity.
Follow up Assign missing criteria, unexplained exceptions or unresolved actions to the responsible product, facilities or environmental owner; distinguish operating concerns from formal assurance findings.
Financial controls and warehouse providers
-
Adjustment and write-off authorityCan each selected inventory adjustment or write-off be explained and linked to the authority required for it?
Check against Establish the organisation's applicable authorisation and supporting-document requirements for the transaction being reviewed.
Look for Compare adjustment entries with reasons, investigation records, approvals and relevant count or movement evidence; retain missing or conflicting support.
Follow up Refer unsupported entries or unclear authority to the inventory and finance owners. Record the control question without treating a variance as proof of fraud.
-
Custody and reconciliation evidenceCan warehouse and finance records be reconciled without confusing physical quantity, custody, ownership and value?
Check against Agree the reconciliation's purpose, period, records and responsibilities with the relevant inventory and finance owners.
Look for Compare selected stock and transaction records, counts and any applicable external-custody evidence; record unresolved differences and the assertions they affect.
Follow up Assign each gap to its evidence owner and identify any further financial-audit work required; a matching quantity alone does not answer every financial question.
-
Contracted service and qualification evidenceDoes the evidence address both the service a warehouse provider delivers and the qualifications required for this relationship?
Check against Identify the actual service commitments, qualification requirements, review period and people responsible for each decision.
Look for Compare selected service records and exceptions with current qualification or assurance evidence relevant to the required scope.
Follow up Keep performance, qualification and renewal questions separate. Request missing evidence and assign the decision rather than treating one favourable document as settling the whole relationship.
-
Charged activity, units and ratesCan selected warehouse charges be traced to the applicable agreement and the activity or unit being billed?
Check against Identify the relevant contract and rate version, charging basis, period and authority for resolving a dispute.
Look for Compare invoice lines with available movement, storage or service records and documented exceptions; retain gaps or inconsistent interpretations.
Follow up Record the disputed point and supporting evidence, then refer it to the commercial or finance decision owner without assuming entitlement or savings.
Responsibilities and follow-through
-
Purpose, criteria and responsibilitiesIs everyone clear about the decision this review supports and what each participant is responsible for?
Check against Record the purpose, scope, criteria, intended users and any required assessor competence or independence.
Look for Compare the review brief with responsibilities understood by the sponsor, evidence providers, assessor and action owners; identify missing authority or conflicting expectations.
Follow up Resolve the commissioning gap with the relevant decision maker before treating a generic checklist as the agreed scope.
-
Evidence coverage and limitationsCan a reader tell what was examined, what was not and where the evidence remains uncertain?
Check against Establish the review's coverage, period and evidence needs against its actual purpose and criteria.
Look for Record selected locations, goods, shifts and transactions, together with missing records, conflicting accounts and reasons for exclusions.
Follow up Limit each conclusion to its support, identify what additional evidence would change the decision and name who should obtain or assess it.
-
Action ownership, resources and escalationDoes each finding have a next action and someone with the authority or support to move it forward?
Check against Agree the action owner, decision owner, required resources, target date and escalation route for unresolved dependencies.
Look for Compare recorded actions with commitments, available authority and the decisions still outstanding; distinguish doing the work from approving resources.
Follow up Make the blocked decision explicit and take it to the responsible person rather than repeatedly assigning work the team cannot complete.
-
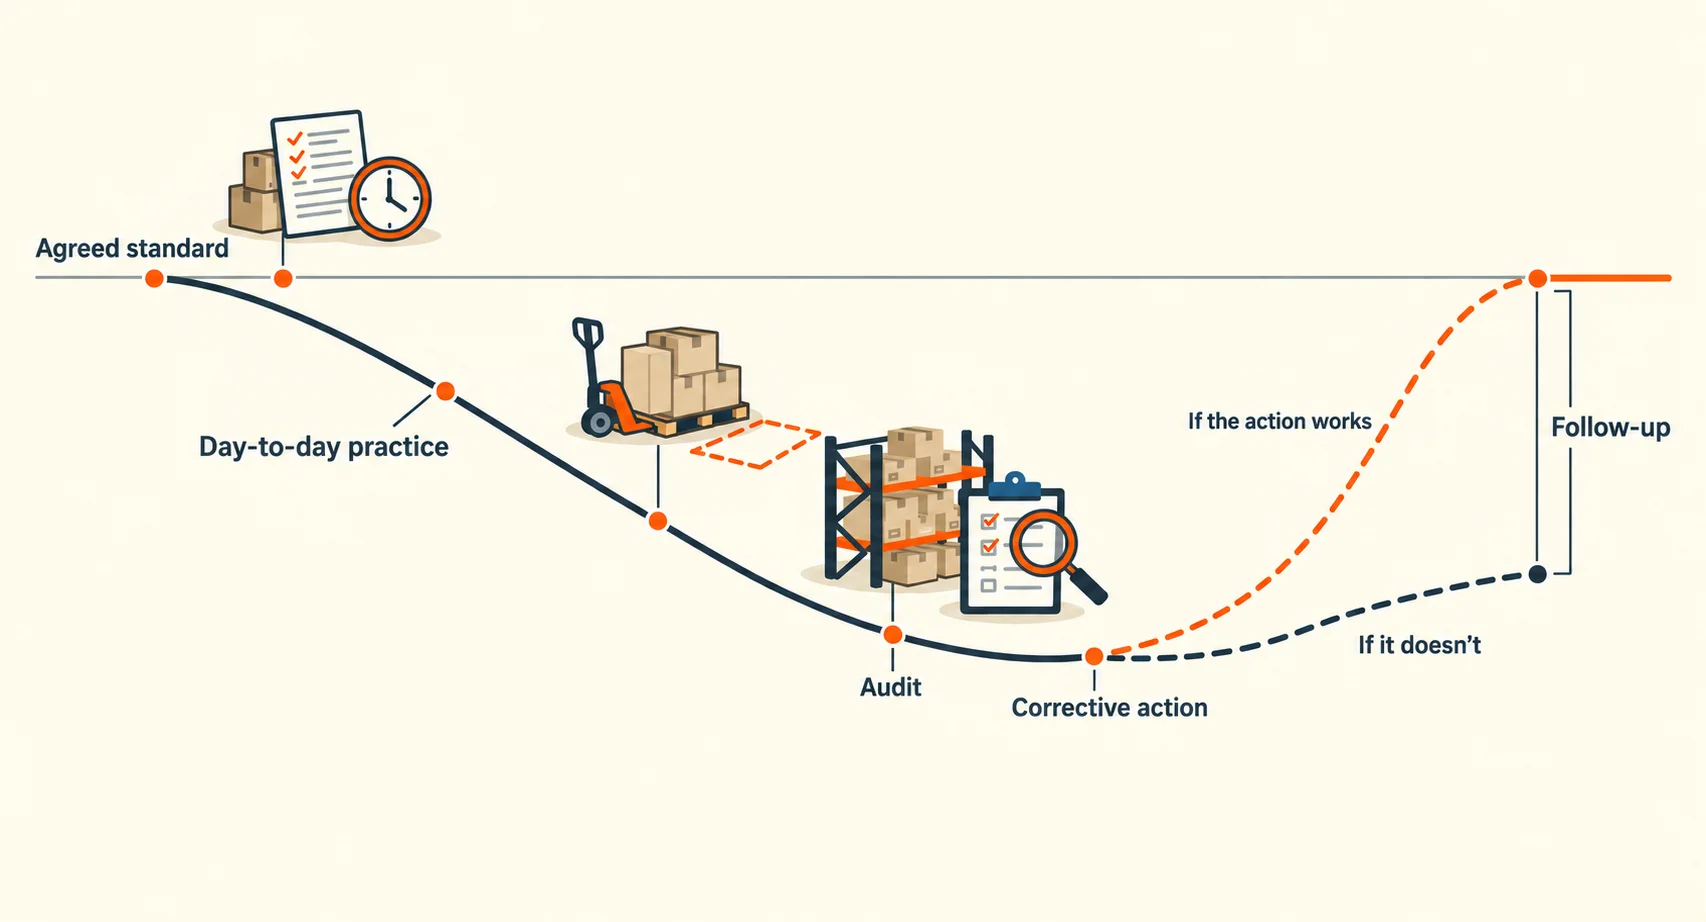
Verification and recurring findingsWhat shows that an action addressed the finding, and what happens if the concern returns?
Check against Agree what effectiveness means for the finding, who will check it and under which relevant operating conditions.
Look for Compare reported completion with follow-up observations, records and recurring exceptions; retain limitations and any unresolved part of the finding.
Follow up Record further work where effectiveness remains uncertain. Distinguish verified operating results from wider financial benefits that have not been demonstrated.
Take the 28 checks onto the warehouse floor, then record findings and actions in the workbook.
Excel and PDF audit packPreview pack contents and download
Bring these 28 checks into an editable working record and printable floor sheets, with examples to help you record findings and assign follow-up.
- Editable Excel workbook: plan the review, record evidence and track findings, action owners and verification.
- Printable PDF sheets: take the checklist onto the warehouse floor and make notes as you review.
- Completed examples and a management review template: see how a stock investigation and provider review become findings, assigned work and decisions to follow up.
Your audit pack is ready
Plan the audit around the decision
If you are commissioning the review, tell the reviewer what you need to decide. “Why do these stock differences keep returning?” or “What do we need to resolve before renewing this provider?” gives the work a purpose.
- Agree the scope. Name the site, activities, goods and period to review. Include the busy shifts or unusual conditions that matter to the concern.
- Agree what to check against. Gather the relevant procedures, service commitments and product requirements. Resolve gaps or disagreements about what was required.
- Arrange access to the evidence. Identify who can provide the records and explain the work. Agree how the reviewer will report missing or conflicting information.
- Plan the handover. Decide who will receive the findings, authorise work or resources, and check that actions have worked.
- Purpose and criteriaWhat decision does this review support, and which requirements apply?
- EvidenceWhat do the records, observations and worker accounts establish?
- Finding and uncertaintyWhat differs from the requirement? What remains unexplained?
- Action or decisionWho owns the next step, and what authority or resources do they need?
- VerificationWhat evidence will show whether the action worked?
Example: should the business add warehouse space?
Suppose warehouse cost per order has risen and a director is considering more space. Commission the review to explain the increase and compare options before approving expansion. Compare order volume and mix, usable storage, labour hours, overtime, rework and outsourced charges over the same periods. Keep service commitments alongside the costs.
Observe when space or work backs up, then test the explanations against the records. More stock held for longer, an awkward order mix, a staffing constraint and work concentrated into a short window call for different responses. Ask the reviewer to report which explanation the evidence supports, the options still worth testing, and the cost and service implications of each. An average occupancy figure alone does not establish the need for another building.
Check what happens on the warehouse floor
Start with a manageable selection of items, transactions or work periods relevant to the concern. Record what you examined so the next person can understand how far the finding extends.
- Compare records, direct observation and worker accounts. Keep conflicting accounts visible.
- Include relevant operating conditions in the review, rather than assuming one quiet shift represents every shift.
- For a stock count, consider keeping recorded quantities out of the counter’s view while retaining the identifiers needed to count the right item and unit. [1]
Ask workers what happens when they report an exception. At one distribution centre studied by Barratt, Kull and Sodero, workers had to notify a supervisor when there was insufficient stock for an order. The researchers described the effect:
This policy impaired employee productivity and, thus, reduced their productivity bonuses.
In your own review, ask whether the way performance is measured makes an exception difficult to report. Compare what workers describe with the procedure and the records.
Example: review a stock location
Choose one item and ask why it is stored in that position. Watch a pick and a refill, paying attention to how people reach and handle the stock and use the space in front of the rack.
Why is this item stored here?
Examine the work
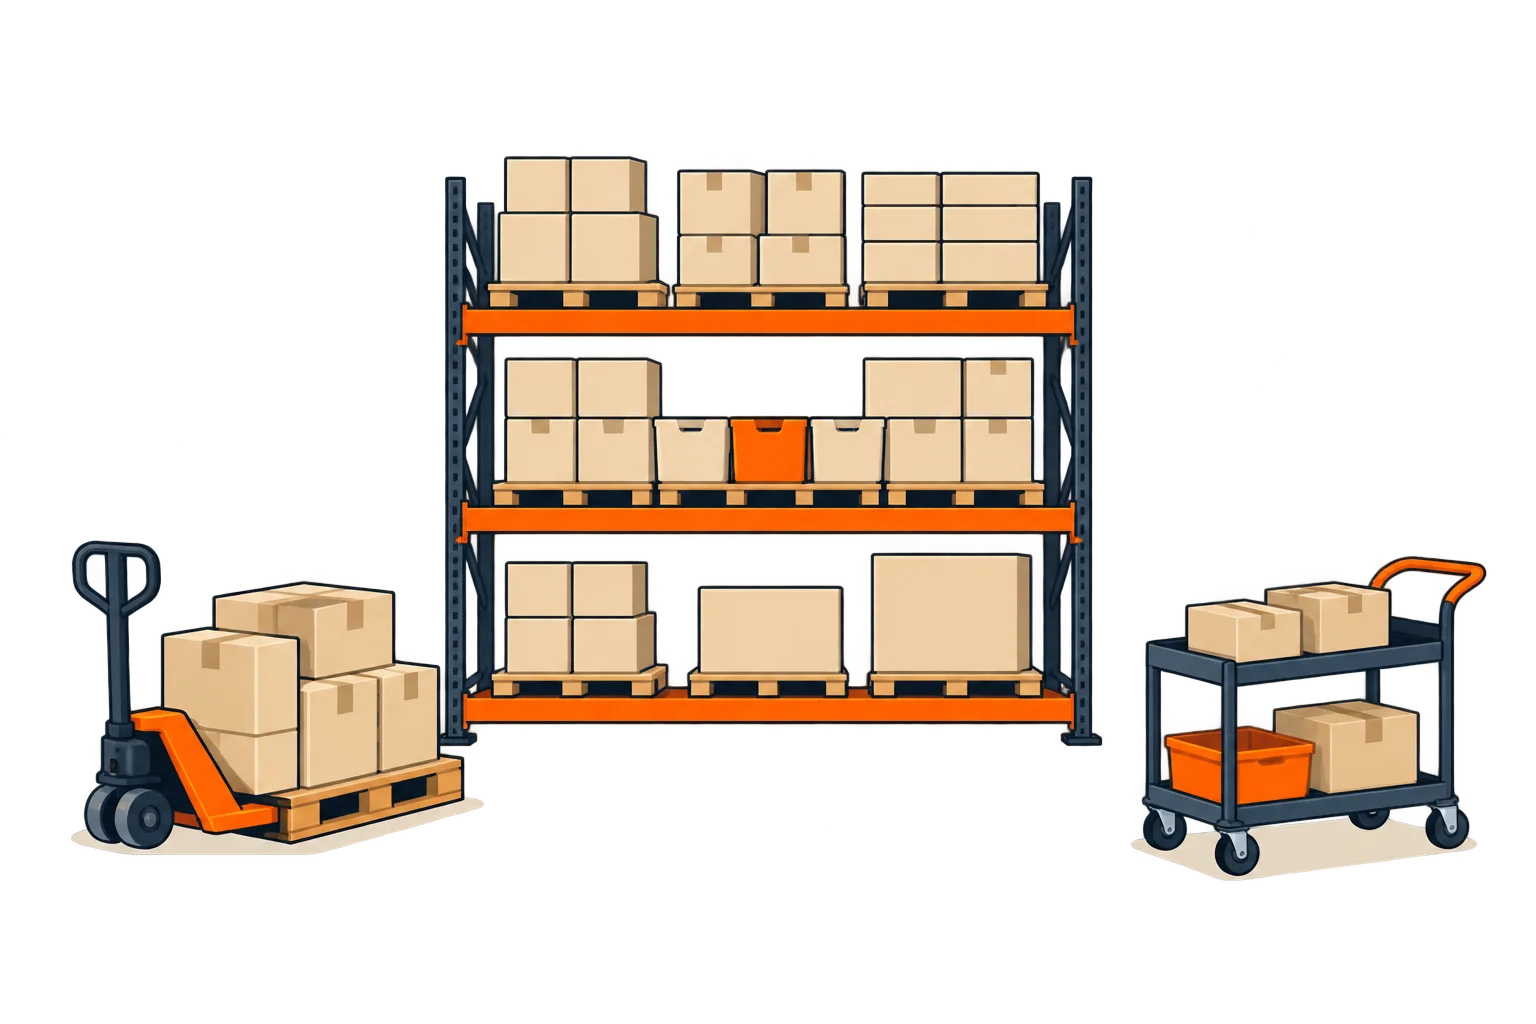
Picking access
Each pick repeats the reach and lift from this shelf to the cart.
Replenishment access
Refilling the shelf needs access for the incoming load and its equipment.
Shared working space
Picking and refilling use the same space in front of the rack.
Compare those observations with how often the item is picked, its handling requirements and the workers’ explanation of the placement. Record any constraint and the evidence for it before proposing a move.
Stock discrepancies and financial controls
When a count differs from the record, retain the count notes and compare the same item, unit, location and time. Trace receiving records, picks, transfers and dispatches across the count boundary. Record any adjustment, its authorisation and the explanation still to be established.
Reconciliation also connects warehouse records with finance records. Ask finance to explain how the stock report’s quantities and costs reconcile to the inventory balance in the accounts. Investigate differences, including transactions entered in different periods, so a correction in one system does not leave the other out of step.
Keep custody and ownership distinct. A 3PL may hold a customer’s stock; a business may own goods held elsewhere. Use contracts, warehouse confirmations and movement records to establish whose goods the records describe.
Condition and value need separate attention. Flag damaged, ageing or restricted stock with its quantity and condition, then have finance assess the recorded value using the applicable accounting policy. Warehouse observations inform that decision; a successful count does not settle it. [6]
Follow one item through the record
- ReceiptConfirm the item and unit.
- Stock recordIdentify the location and recorded balance.
- MovementsCheck what changed around the count.
- Count and recountRetain the observed quantity and timing.
- AdjustmentRecord the authority and any unresolved cause.
A Martin County public audit recommended a separate verification count where a variance exceeded management’s tolerance:
The verification count should be performed by a staff member who did not participate in the original count.
Example: 11 counted, 12 recorded
Suppose the team counts 11 units in a bin and the inventory record shows 12. A recount confirms 11. The team now needs to establish whether the record and count describe the same item, handling unit and point in time.
Beneath a stock discrepancy
12 recorded 11 counted
Count or comparison error
Recording error
Time pressure
Handover gaps
Uncaught errors
No one owns the outcome
Information doesn’t reach other crews
Normalised assumption: goods out the door = job done
- Check what could explain the difference. Compare receipts, picks and transfers around the count. Check similar product codes and any change between cases and individual units. Record which explanations the evidence supports and which remain open.
- Give the investigation an owner. The inventory lead follows up the unanswered points. Record any authorised adjustment alongside the investigation, including the evidence used for each.
- Check the next result. If the same difference keeps returning, use the investigation to choose a corrective action and agree how a later check will show whether it worked.
For a related example, see how recurring stock corrections can reveal problems in automated replenishment.
A completed finding and follow-up
Here is one fictional continuation of the 11-versus-12 example. The procedure, dates and record references below are illustrative; they show how to document a supported conclusion while leaving a wider question open.
- Scope and criterion. Review SKU-104, bin A-01, in individual units at 09:00 on 6 October 2026. The example site's inventory procedure, INV04 version 3, requires stock issues to be posted before dispatch.
- Evidence and finding. Count C104 and independent recount RC104 both show 11; snapshot S104 shows 12. Pick P418 and dispatch D418 show one unit leaving at 16:40 on 5 October. Queue record Q418 shows its stock issue still pending at the comparison time. That unposted issue explains this difference. It does not establish why earlier discrepancies occurred.
- Immediate correction. At 11:00 on 6 October, the inventory manager authorises posting the one missing issue against D418. The recorded quantity becomes 11. Do not also enter a separate one-unit adjustment for the same movement.
- Accountable action. The inventory lead assigns a named handover owner and a pending-issue review before release, effective by 17:00 on 6 October. Handover record H104 records the change and the cover arrangement.
- Verification. At 15:00 on 9 October, the warehouse manager records check V104: all 20 selected dispatches across three shifts on 7–9 October had their issues posted before release; the selected bin also matched its record.
The correction and the tested control have evidence within this sample. Earlier recurrences remain a separate investigation. Keep that limitation with the result rather than describing the whole inventory process as fixed.
Compliance and customer audits
If you are preparing for a customer’s audit, ask for the scope and evidence request before gathering documents. Confirm which goods, activities and dates the review covers, which requirements apply and who can answer questions about them.
Establish which requirements apply
For each important requirement, record its source and why it applies: a law or authorisation, a customer contract, an internal procedure or a voluntary standard the business has adopted. Include the version, goods, activities and period covered. A customer or regulatory review may arrive with its criteria already set; an internal improvement review still needs an agreed basis for judging the work.
Keep those criteria distinct. A favourable assurance report answers only the scope it covers; it does not settle every customer requirement. If two parties interpret a requirement differently, record the disagreement and identify who can resolve it before issuing a conclusion that depends on that interpretation.
Agree who can judge the evidence and authorise action
Choose reviewers who understand the work and can assess the relevant evidence, including any product or technical knowledge the review needs. Decide how any required independence will be achieved. If someone is examining a process they designed or manage, make that involvement visible and arrange another reviewer for an affected judgement where needed.
Name who supplies the records, who reaches each conclusion, who can approve corrective resources and who checks the result. One person may hold several roles, but an assignment without the necessary authority leaves work blocked.
Missing monitoring records establish an evidence gap; they do not, by themselves, establish the condition of the goods. State which conclusion remains unsupported and what evidence would resolve it. Take blocked access, disputed criteria or an unfunded action to the person who can decide, with the consequence, options and decision date. Keep the unresolved limitation in the report.
United Warehouse describes customers bringing their own reviews into the operation:
We are routinely audited by many of our customers, and even by their customers.
Example: trace a removal from a UK customs warehouse
Follow goods leaving the warehouse through the records to check that the entries connect and were made at the right time. In a closing stock balance system approved by HM Revenue & Customs (HMRC), the commercial records and duty-management system together form the stock account.
- Start with the commercial record. Check that the consignment details, quantity and removal date were entered before the goods left.
- Follow the audit trail. Ask how the commercial entries feed into the duty-management update.
- Check the update timing. Confirm the duty-management system was fully updated as soon as information became available, before midnight of the following warehouse operation day. [5]
Agree the removals and period to review with the person responsible for the warehouse’s customs authorisation, using the requirements of its approved arrangement.
Turn findings into decisions
A useful finding explains what happened, why it matters and what decision or action is needed.
- State the finding and its limits. Record the requirement, what you observed and the items or periods examined. Include missing or contradictory evidence.
- Make the next step clear. Name the action owner, due date and any approval, resource or specialist input needed.
- Agree how it will be checked. Record who will verify the result, when and what evidence they will need.
Example: reviewing a warehouse provider before renewal
Suppose dispatches from a 3PL have been late, a customer has questioned the storage conditions and some warehouse charges are disputed. A director needs the review to explain what each concern means for the renewal decision.
The following fictional review covers selected transactions from 1–7 October 2026, with a management decision recorded on 8 October. The agreements, records and amounts are illustrative. The billing figures exclude VAT and other invoice lines.
- Service finding. SLA12 version 2 requires the selected orders to be ready for dispatch by 17:00. Order, staging and handover records establish that four of the 12 selected orders were late. The cause remains unresolved. The service lead must report the operating evidence and proposed response by 10 October; the warehouse manager will verify the agreed service criterion after that response is implemented.
- Storage conclusion still open. Customer specification CS2 version 2 requires dry storage, but a condition-record gap on 2 October leaves the evidence for the affected goods incomplete. The quality lead must assess their condition and report the evidence and any required action by 9 October. Neither the missing record nor an unrelated certificate settles acceptability.
- Billing finding resolved. The invoice charges 120 pallet-days at £2, or £240. The activity records confirm 120 pallet-days, but the signed rate schedule, version 2 effective 1 October, sets £1.50 per pallet-day: £180 for the same period and activity. The provider used the superseded rate. The commercial lead agrees credit CN82 for £60; the finance controller checks the credit and net £180 charge on 8 October.
Recorded management decision, 8 October: request the service plan and quality assessment before making the final renewal decision, with the named owners and dates above. Ask the commercial lead to confirm the available options against the contract timetable. The invoice line is resolved; service and product questions remain open. This gives the director a decision record without manufacturing a single pass score for the relationship.
Get the checklist in Excel and PDF
Use the workbook to assign actions and track verification; print only the floor sheets you need.
Bring these 28 checks into an editable working record and printable floor sheets, with examples to help you record findings and assign follow-up.
- Editable Excel workbook: plan the review, record evidence and track findings, action owners and verification.
- Printable PDF sheets: take the checklist onto the warehouse floor and make notes as you review.
- Completed examples and a management review template: see how a stock investigation and provider review become findings, assigned work and decisions to follow up.
Your audit pack is ready
How often should you audit?
- Routine checks: follow the requirements for the task.
- Planned reviews: choose a scope and interval informed by the operation and its obligations.
- Triggered reviews: respond to a material change, recurring discrepancy or incident.
- Follow-up checks: test whether an action worked.
These are different purposes, not a universal monthly or quarterly schedule.
Inventory counts have their own coverage and timing. Cycle counting covers inventory through successive selections; a full physical count covers the defined inventory at a point in time. [1] A wider warehouse audit examines the work and controls behind the records.
Two ways to organise a stock count
Cycle counting
Selected items or locations in successive counts.
Cover inventory over time
Full physical count
All inventory within the defined count boundary.
Count at a defined point in time
For either method, define
- Item and unit
- Count boundary and time
- Stock movements
- Recount and reconciliation
Technology and the people doing the work
Records, photographs and warehouse systems help reviewers reconstruct events. The people doing the work can explain gaps and exceptions in those records.
Dock scheduling shapes the work an audit needs to understand. When arrivals bunch together, staging space and the team’s time come under pressure. Compare planned appointments with actual arrivals, then trace the loads through receiving or dispatch to check how staging, checks and stock entries were handled. Ask the team what changed during the peak and compare its account with the records.
An illustrative comparison of bunched arrivals, rushed staging and audit errors with spaced appointments, orderly staging and audit readiness.
First Come First Serve
Rushed staging
Audit errors
Scheduled shipping & receiving
Clean staging
Audit ready
A useful audit leaves people with an understandable finding, a practical next step and the support to carry it out. The aim is to make sure the system supports the work they do.
References
- 1U.S. General Accounting Office (2002). Best Practices in Achieving Consistent, Accurate Physical Counts of Inventory and Related Property. GAO-02-447G. Count-method definitions, p. 20; blind-counting guidance, Key Factor 8, pp. 39–41, including its context and alternative controls.
- 2Barratt, Kull and Sodero (2018). Inventory record inaccuracy dynamics and the role of employees within multi-channel distribution center inventory systems. Journal of Operations Management, 63, pp. 6–24. The quoted passage is on p. 17 of the author manuscript.
- 3Martin County Clerk of the Circuit Court and Comptroller (2021). Utilities Warehouse Inventory. Audit 2021-A-0001, p. 24, Recommendation 4.
- 4United Warehouse. Warehouse Facility Audits. Operator self-description, customer-audits section.
- 5HM Revenue & Customs (2025). Duty management and closing stock balance systems. Guidance for the stated HMRC customs-warehousing context.
- 6Public Company Accounting Oversight Board. AS 1105: Audit Evidence, paragraph .11 distinguishes existence, valuation and rights. AS 2510: Auditing Inventories, paragraph .14 addresses goods held by outside custodians.